
By Paul de Neuville, Paris correspondent, for Eurasia Business News – October 4, 2026. Article no 3192
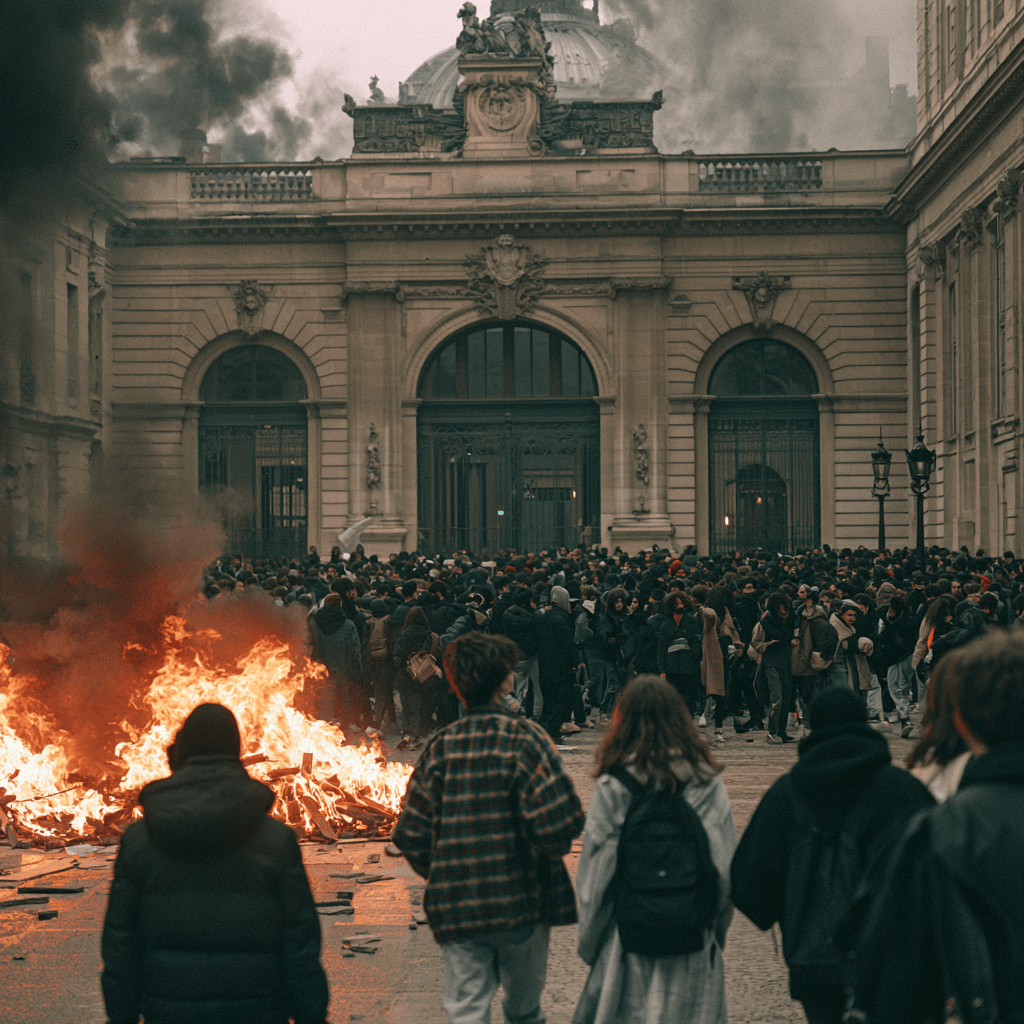
France entered October facing a dangerous combination of rising borrowing costs, political instability and escalating protests in high schools. The country’s benchmark 10-year government bond yield approached 4.9%, while the draft 2027 budget imposed tens of billions of euros in savings on an already strained public sector. At the same time, student demonstrations over teacher shortages, overcrowded classrooms and deteriorating school buildings spread across the country, with clashes and fires increasing pressure on the government.
The protests have transformed France’s debt debate from a financial-market issue into a wider social and political crisis. Prime Minister Sébastien Lecornu is attempting to reduce the budget deficit while preserving investor confidence, but the measures required to stabilize public finances are colliding with demands for better public services.
French Bond Yields Near 5%
France’s 10-year OAT yield rose to approximately 4.914%, around 139 basis points higher than a year earlier and close to its highest level in decades. Investors are demanding a larger premium to hold French debt because of concerns about the country’s debt trajectory, political fragmentation and the government’s ability to pass its 2027 budget.
French borrowing costs have risen alongside global Treasury yields. The U.S. 10-year yield has moved above 5%, while European bond markets have also been hit by persistent inflation and expectations of higher interest rates.
France’s public debt is projected to reach 121.7% of GDP in 2027. The government has proposed a fiscal adjustment worth €54 billion, including €43 billion in new measures, in an effort to reduce the deficit to 5% of GDP.
Debt-service costs are becoming one of the largest items in the French budget. Under the draft plan, interest payments are expected to reach €74.5 billion, surpassing education spending. This change is politically sensitive because it means France could spend more servicing existing debt than financing schools, universities and teachers.
High School Protests Spread
The student protests began in schools around the Paris region before spreading nationwide. Demonstrators have complained about teacher shortages, overcrowded classrooms, long school days, overheated buildings and deteriorating facilities.
By October 2, approximately 400 high schools—around one in 10 nationwide—were closed or disrupted. More than 700 schools had reportedly experienced some level of disturbance, while students, police officers and education workers were injured during confrontations.
The unrest escalated after students blocked school entrances, burned bins and vehicles, and clashed with riot police. Fires were reported at several schools, while a teacher in Marseille was accidentally splashed with petrol during one incident. Authorities made hundreds of arrests, most involving teenagers and young migrants.
| Pressure point | Reported impact |
|---|---|
| Teacher shortages | Classes disrupted and staff absences increase |
| Overcrowding | Students report difficult learning conditions |
| Poor infrastructure | Dilapidated and overheated buildings fuel anger |
| Budget restrictions | Planned spending controls intensify tensions |
| Police response | Hundreds arrested and clashes reported |
| School disruption | About 400 high schools closed on October 2 |
Budget Cuts Fuel Political Crisis
The protests erupted just as the government presented its draft 2027 budget. The education budget is scheduled to increase by 1.7% to €65.53 billion, excluding teacher pensions. But with inflation and operating costs still high, the increase is viewed by many educators as insufficient to address staffing shortages and infrastructure problems.
The government argues that France cannot continue increasing spending without addressing its debt. But students and teachers see the fiscal strategy as evidence that public services are being sacrificed to satisfy bond investors and European budget rules.
This conflict has placed Lecornu’s government in a difficult position. If it increases education spending, it risks weakening its deficit-reduction plan. If it maintains spending limits, protests could spread and undermine parliamentary support for the budget.
The unrest is also becoming part of the political campaign ahead of next year’s presidential election. President Emmanuel Macron is constitutionally barred from seeking a third consecutive term, and rival parties are using the protests to attack the government’s economic and social policies.
France has been caught in a debt trap since 2024 because its deficits remain large while interest costs and borrowing rates have risen faster than its ability to reduce spending or lift growth. The result is a self-reinforcing cycle: the state borrows to finance deficits, higher debt increases interest payments, and those payments make the next deficit harder to close.economy-finance
In 2024, France’s general-government deficit reached 5.8% of GDP—well above the EU’s 3% ceiling—while debt rose to about 112.7% of GDP. The deficit was not a one-off shock: it remained 5.1% in 2025 and is expected to be about 5.4% in 2026. Consequently, debt is projected to rise from 115.6% of GDP in 2025 to around 121.7% in 2027.economy-finance.
Read also : Tax Management strategies for Digital Nomads
The central problem is the interest-growth gap. When the effective interest rate on new debt exceeds nominal economic growth, debt rises unless the government runs a sufficient primary surplus. France instead continues to run large primary deficits. Its 10-year borrowing cost has climbed from near-zero rates in 2020 to around 4.9%, sharply raising refinancing costs.
Interest payments are increasingly crowding out public priorities: they are forecast around €65 billion in 2026 and could exceed €90 billion in 2027. At the same time, political fragmentation makes tax rises, pension changes and spending cuts difficult to enact.
This does not mean France faces imminent default. But without credible deficit reduction, stronger growth or lower yields, its debt dynamics will remain unstable.
Why Markets Are Watching France
France remains one of the eurozone’s largest economies and one of its biggest government-debt issuers. A sustained rise in OAT yields would increase refinancing costs and make deficit reduction even more difficult.
Wider spreads against German Bunds could also affect French banks, institutional investors and companies that use government bonds to price loans. Higher borrowing costs could slow housing, investment and household consumption, placing additional pressure on economic growth.
Read also : 7 ways to retire comfortably with $1 million
The danger is a self-reinforcing cycle: political instability makes investors demand higher yields; higher yields increase debt-service costs; higher interest payments force deeper spending cuts; and those cuts fuel further social unrest.
A Test of Government Authority
France’s crisis is not yet equivalent to a sovereign-debt emergency, but the warning signs are becoming harder to ignore. Bond yields near 5%, debt above 120% of GDP, a fragile parliamentary majority ahead of presidential and legislative elections in 2027 and nationwide high school unrest are converging at the same time.
Read also : The Private Investor Deal Evaluation Handbook
The French government must now show that it can protect essential public services and supporting its economy while restoring fiscal credibility. That will require more than announcing a €54 billion savings plan. It will require political compromise, credible education funding and evidence that France can reduce its deficit without intensifying the social tensions already visible outside the country’s schools and streets.
Our community already has nearly 355,000 readers!
Subscribe to our Telegram channel
Follow us on Telegram, Facebook and Twitter
© Copyright 2026 – Eurasia Business News. Article no. 3192

