
By William Collins, consultant in stock markets – Eurasia Business News, November 5, 2026. Article no 3244
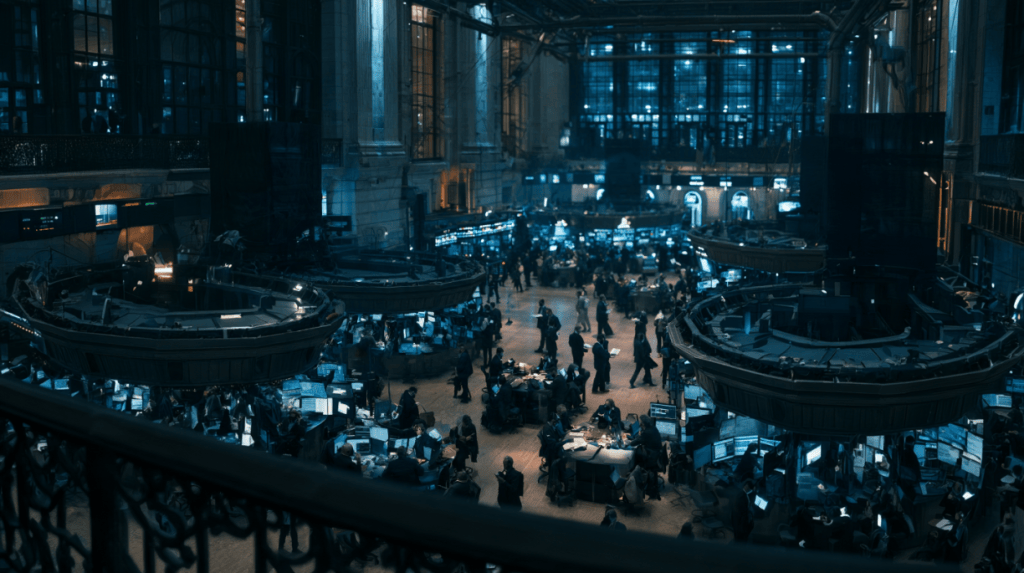
U.S. stocks plunged on Thursday, November 5, as investors abandoned semiconductor and data-center shares, reversing enthusiasm after the midterm elections. The supplied intraday update showed the Nasdaq Composite falling more than 5%, the S&P 500 losing approximately 3.5% and the Dow Jones Industrial Average dropping around 1,300 points. Qualcomm’s disappointing smartphone-chip sales intensified concerns about technology demand.
The selloff put the Nasdaq on course to enter correction territory, generally defined as a decline of at least 10% from a recent high. These were intraday readings, not confirmed closing results. The distinction matters during a session in which losses widened considerably after the opening bell.
Nasdaq Selloff Deepens as Post-Election Optimism Fades
Reuters reported the Nasdaq down 3.09% at 9:57 a.m. Eastern Time, with the S&P 500 losing 1.66% and the Dow declining 351.87 points. The larger losses in the supplied update therefore describe a later stage of the selloff rather than the market’s opening position.
Thursday’s retreat followed Wednesday’s broad post-election rally. Kitco’s morning report put the previous session’s gains at approximately 3% for the Dow, 1.58% for the S&P 500 and 1.44% for the Nasdaq. Accordingly, Thursday’s Dow decline should not be described as its second consecutive four-digit loss: Wednesday was a strong advance.
The rapid reversal suggested that relief over the election outcome had not resolved concerns about earnings, valuations or the costs of expanding AI infrastructure. Chip and data-center companies had already shown weakness before Thursday’s regular session began.
Chipmakers and Data-Center Suppliers Lead the Declines
The Philadelphia Semiconductor Index fell approximately 7.1% in early trading, with Nvidia, AMD, Intel and Marvell among the companies weighing on the sector. That performance showed investors reducing exposure across the semiconductor supply chain, rather than reacting only to one company’s results.
At the later checkpoint supplied for this report, losses were particularly severe among memory, storage and infrastructure-related companies:
| Company | Reported intraday decline |
|---|---|
| Sandisk | 20.6% |
| Astera Labs | 18.4% |
| Nebius Group | 18.2% |
| Western Digital | 17.1% |
| Lumentum | 16.7% |
| Seagate Technology | 16.3% |
| AMD | 16.0% |
| Micron Technology | 15.7% |
These user-supplied readings were not independently verified closing prices. Their significance lies in the pattern: investors were reassessing businesses whose growth expectations depend heavily on continued infrastructure investment.
Qualcomm Earnings Expose Smartphone Weakness
Qualcomm provided a company-specific catalyst. Its fiscal fourth-quarter handset revenue fell 26% year over year to approximately $5.14 billion, below the $5.25 billion analysts expected. Management attributed the weakness partly to industry-wide memory dynamics affecting the smartphone market.
Total quarterly GAAP revenue declined 8% to $10.322 billion. Adjusted earnings of $2.17 per share slightly exceeded expectations of $2.16, but that narrow beat did not offset concerns about the handset business and future profitability.
The results illustrate why an earnings beat does not necessarily produce a rising share price. Investors assess the composition and sustainability of revenue, not simply whether one headline measure clears consensus. Qualcomm’s automotive revenue grew 89%, providing diversification, but smartphone weakness dominated the immediate reaction.
Why the Midterm Results Matter for the AI Trade
The supplied market commentary linked the rotation away from AI infrastructure to expectations that a Democratic-controlled Congress could bring greater scrutiny to the data-center buildout. That is a market interpretation, not evidence that new restrictions had already been enacted.
Investors must distinguish between political expectations and actual changes to project economics. Permitting, electricity availability, equipment costs and customer spending commitments can influence construction schedules independently of congressional control.
Thursday’s early market reporting confirmed pressure on chip and data-center shares after the Democratic sweep, but it did not establish that election results alone caused the decline. Qualcomm’s earnings and broader demand concerns provided additional explanations.
Strong Results Fail to Protect Every Technology Stock
The supplied earnings summary described declines in SiTime, MACOM and Coherent despite better-than-expected results. It reported SiTime adjusted earnings of $4.01 per share on $298.7 million in revenue, while MACOM posted adjusted earnings of $2.09 and revenue of $424.8 million.
Those figures are presented here as supplied earnings data rather than independently verified releases. They nevertheless illustrate the distinction between operating performance and market expectations: during a broad valuation reset, investors may sell companies delivering strong growth because they question future demand or the price previously paid for that growth.
Read also : Tax Management strategies for Digital Nomads
The supplied claim that the Magnificent Seven lost $1 trillion also requires a timestamp and consistent market-capitalisation calculation. It should not be presented as a verified closing total.
Oil Rebounds, but Brent Remains Below $100
Oil recovered during European morning trading after Wednesday’s sharp decline. Kitco reported Brent futures approximately 1.6% higher at $96.15 per barrel, with WTI gaining 0.6% to around $88.64. These were intraday quotations.
On Wednesday, Brent settled at $94.62, down 8.7%, while WTI closed at $88.12, losing 8.3%. Expectations that the election results could increase pressure for an Iran settlement helped drive that retreat, although an agreement remained uncertain.
Gold and Silver Prices According to Kitco
Gold’s bid price was at $4,088.30 per troy ounce at 11:08 a.m. EST, up $28.40, or 0.70%. Its session range was $4,057.50–$4,148.00.
Read also : Gold : Build Your Wealth and Freedom
Silver diverged, trading at a bid of $51.62 per ounce, down $0.49, or 0.94%. Earlier Kitco reporting had both metals higher, demonstrating why timestamped quotations matter.
The session’s defining theme was repricing: investors reconsidered how much future AI growth justified current valuations, even as cheaper oil and firmer gold offered a different picture elsewhere in financial markets.
Our community already has nearly 346,000 readers!
Subscribe to our Telegram channel
Follow us on Telegram, Facebook and Twitter
© Copyright 2026 – Eurasia Business News. Article no. 3244

