
By Paul de Neuville, Paris correspondent, for Eurasia Business News – October 6, 2026. Article no 3199
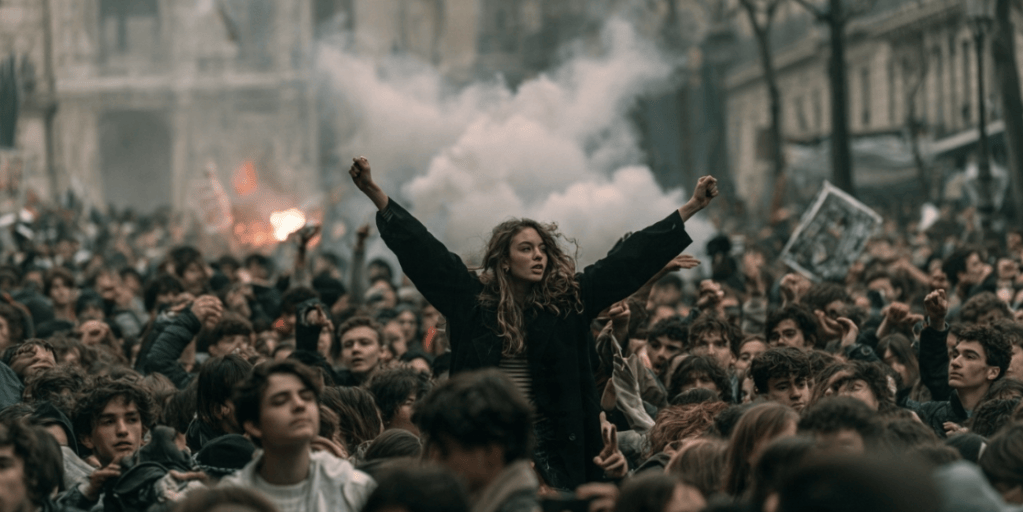
Photo : Blockade of highschool by French teenagers in Paris on October 6, 2026. Photo credit : Eurasia Business News
France is facing a widening political and economic crisis as high-school blockades and street clashes coincide with rising borrowing costs, a severe budget deficit and record public debt. The country’s financial difficulties are increasingly colliding with social unrest, creating pressure on Prime Minister Sébastien Lecornu’s government to restore order while producing a credible budget.
On Tuesday, October 6, an estimated 266,000 people joined demonstrations across France, including approximately 56,000 in Paris, according to the Interior Ministry. Organizers put the national turnout closer to 450,000. Police reported 488 arrests and 48 injured security officers, while hundreds of schools were fully or partially closed.
The protests, described by student groups as “Act Three,” began with high-school blockades and expanded into a national movement involving students, teachers and parents. Demonstrators have cited overcrowded classrooms, teacher shortages, deteriorating school buildings, long school days and stress linked to the university-admissions system.
High-School Protests Escalate
The government has responded by suspending high-school classes for part of the day between Wednesday and Friday. Lecornu said the pause would give school leaders time to organize internal discussions with students and address their concerns.
Authorities face a difficult balance. They must protect students and staff while preventing further damage, but heavy police intervention risks deepening anger among young people. Reuters reported that more than 5,000 people had been arrested since the movement began, while education officials said dozens of schools had suffered serious damage.
On Tuesday, the Interior Ministry said 266,000 people participated in demonstrations nationwide, while independent organizers estimated turnout at 450,000. The gap reflects the political sensitivity of the protests and the challenge of measuring participation during a fast-moving national mobilization.
The unrest is also exposing wider concerns about public services. Students protesting school conditions are effectively arguing that years of fiscal pressure have weakened institutions that families rely on every day.
France’s Debt Burden Deepens
France’s financial position has deteriorated as higher global interest rates raise the cost of refinancing government debt. Public debt reached roughly €3.6 trillion in the second quarter of 2026, equivalent to about 119% of gross domestic product, according to reported official data.
France’s public debt is projected to reach 121.7% of GDP in 2027. The government has proposed a fiscal adjustment worth €54 billion, including €43 billion in new measures, in an effort to reduce the deficit to 5% of GDP.
The government deficit is expected to reach approximately 5.4% of GDP this year, well above the European Union’s 3% fiscal limit. The proposed 2027 budget aims to cut the deficit to 5% through about €54 billion in spending reductions and additional revenue measures.
Read also : The Private Investor Deal Evaluation Handbook
However, reducing the deficit is politically difficult. France has a large welfare state, extensive public services and high structural spending. Attempts to reduce subsidies, pensions, healthcare costs or public-sector employment can quickly trigger opposition from unions, local governments and voters.
At the same time, weak growth makes it harder to reduce debt through economic expansion. When output grows slowly, the debt ratio can rise even if the government limits new spending.
Borrowing Costs Overtake Greece and Italy
Investors are demanding a larger premium to hold French government bonds. France’s 10-year borrowing costs have risen above those of Greece and Italy, countries once viewed as the weakest links during the eurozone debt crisis. The spread between French and German 10-year bonds has also reached levels associated with the 2011–2012 crisis.
Higher yields increase the government’s debt-servicing bill. The French audit office has warned that annual interest payments could approach €100 billion by 2029, potentially becoming one of the largest items in the national budget.
This creates a dangerous feedback loop: higher interest rates increase debt-service costs, which widen the deficit, forcing the government to borrow more. Investors may then demand even higher yields, especially if political divisions prevent credible fiscal reform.
Taxes, Talent and Emigration
France also faces a competitiveness challenge. High taxes and complex regulations finance extensive public services, but they can discourage investment, entrepreneurship and skilled workers.
Read also : 7 ways to retire comfortably with $1 million
Some business owners, engineers, technology specialists and wealthy taxpayers have moved abroad or considered relocation to countries with lower taxes and more predictable business environments. The departure of highly skilled workers can weaken productivity and reduce the tax base, making it harder to finance public programs.
The government must therefore pursue fiscal consolidation without undermining economic growth. Cutting productive investment, education spending or research could reduce short-term costs while worsening France’s long-term competitiveness.
A Dangerous Political Test
France’s crisis is not the result of one problem. It reflects the interaction of social unrest, high public spending, rising debt, uncontrolled immigration over the past 30 years, elevated interest rates, heavy taxation and political fragmentation.
The high-school protests have made the consequences visible in classrooms and city streets. Unless the government can improve school conditions while presenting a credible plan to stabilize public finances, France risks a cycle in which weaker services generate more protests, protests make reforms harder and delayed reforms increase borrowing costs.
Read also : Tax Management strategies for Digital Nomads
The coming budget debate will determine whether France can restore investor confidence without triggering a deeper social backlash. For Europe’s second-largest economy, the stakes extend beyond domestic politics: prolonged financial instability in France could become a wider risk for the eurozone.
In an interview, French Finance Minister Roland Lescure said he is open to negotiation but will do ‘whatever it takes’ to get the budget through.
Our community already has nearly 355,000 readers!
Subscribe to our Telegram channel
Follow us on Telegram, Facebook and Twitter
© Copyright 2026 – Eurasia Business News. Article no. 3198

